

ArmInfo. The net profit of the Armenian banking system in January-September 2026 slowed in year-on-year growth from 15% to 9%, amounting to 334.4 billion drams or $921.8 million. This is evidenced by the Express Ranking of Armenian Banks as of September 30, 2026, prepared by ArmInfo Investment Company.
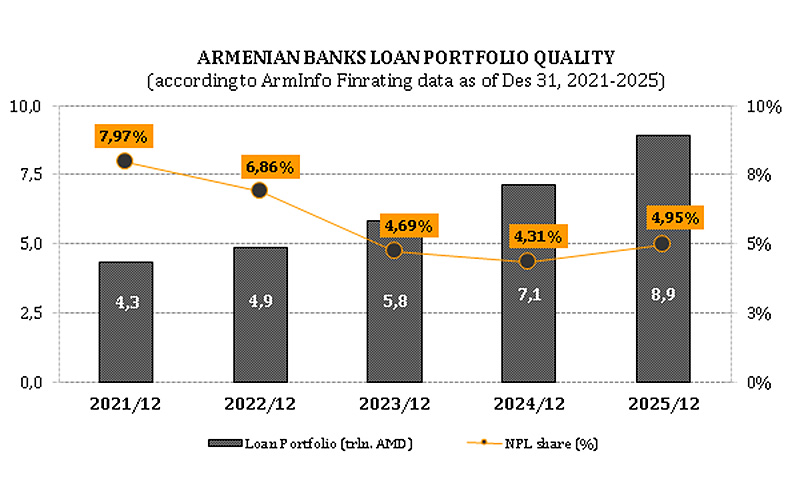
According to ArmInfo analysts, net profit, having returned to natural growth in the last two years supported by active lending, has gradually begun to decline due to the markedly deteriorating quality of portfolios. Considering that over half of non-performing loans have accumulated in the riskiest groups—questionable and hopeless—which continue to grow at a rapid pace, it can be assumed that their periodic write-offs are particularly depressing this indicator.
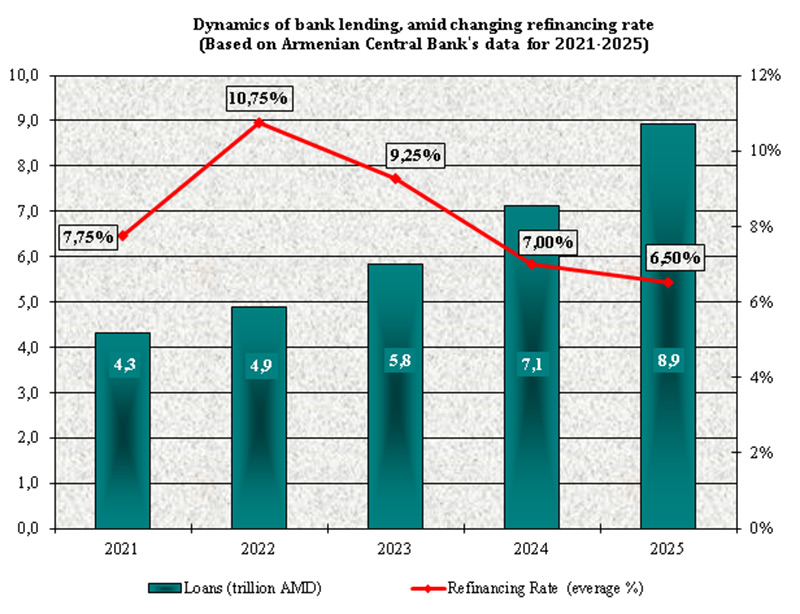
Nevertheless, according to the Ranking, by October 1, 2026, the volume of credit investments and other loans exceeded 9 trillion drams ($24.9 billion), with a slight slowdown in growth from 26% to 24%, and an increase in the dominant share of assets from 60.7% to 62.4%. This allowed assets to increase to over 14.5 trillion drams ($39.9 billion), with annual growth accelerating from 18% to 21%. Moreover, within the asset structure, the annual growth of investments in securities accelerated less noticeably – from 13% to 16% – than balances in nostro accounts – from 2% to 14%, resulting in their volumes equaling 2.5 trillion drams ($6.8 billion each, or a total of 34% of assets).
Total liabilities also accelerated in year-on-year growth from 18% to 22%, exceeding 12.1 trillion drams ($33.5 billion). The share of liabilities to clients increased from 68.8% to 72.9%, while the share of liabilities to banks and other financial institutions decreased from 25.5% to 23.6%. This is the result of an acceleration in the annual growth of liabilities to clients from 16% to 29%, and a slowdown in the growth of liabilities to banks and other financial institutions from 22% to 13%, amounting to 8.9 trillion and 2.9 trillion drams ($24.4 billion and $7.9 billion), respectively.
As a result, the nearly identical 21-22% growth in interest income and expenses observed a year ago slowed to 19% for revenue and accelerated to 26% for expenses, with the volume of expenses for the first nine months of this year amounting to 929.2 billion and 413.7 billion drams ($2.6 billion and $1.1 billion), respectively. At the same time, there was a more noticeable slowdown in the growth rate of non-interest income, from 14% to 7%, compared to non-interest expenses, from 19% to 14%. The latter amounted to AMD 284.8 billion and AMD 354.4 billion ($784.8 million and $976.9 million), respectively. This is explained by the fact that the dominant interest income and expense items—lending and customer liabilities—continued to grow at double-digit rates. Lending slowed, while customer liabilities accelerated. As for the main items of non-interest income and expense—card transactions and money transfers—their growth stalled.
Total capital slowed in year-on-year growth from 17% to 14%, exceeding AMD 2.3 trillion ($6.4 billion). In its structure, the share of authorized capital decreased year-on-year from 49% to 45%, while accumulated profit, conversely, increased from 44% to 47%. The absolute values of these profits amounted to 1.04 trillion drams ($2.9 billion) and 1.1 trillion drams ($2.99 billion), respectively. Specifically, accumulated profit accelerated in year-on-year growth from 13% to 22%, while authorized capital growth slowed significantly from 19% to 5%. The latter was due to only three banks increasing their authorized capital: Fast Bank (by 10.9% in Q2 2026 and by 28.4% in Q3 2026), AMIO Bank (by 10.5% in Q1 2026), and Inecobank (by 14.01% in Q4 2025).
The top 5 banks by key balance sheet indicators in the banking sector remained unchanged.
In terms of assets, the top five, with a total coverage of over 62%, are represented by Ardshinbank, Ameriabank, Acba Bank, INECOBANK, and AMIO Bank.
Ameriabank, Ardshinbank, Acba Bank, INECOBANK, and AMIO also lead in loan investments, with a total coverage of approximately 66%. Bank.
The top 5 banks in terms of securities investments are Ameriabank, Ardshinbank, AMIO Bank, Evocabank, and INECOBANK, accounting for a combined total of over 54%. In terms of customer liabilities, Ardshinbank, Ameriabank, Acba Bank, INECOBANK, and AMIO Bank account for a combined total of approximately 64%. In terms of total capital, Ardshinbank, Ameriabank, Acba Bank, AMIO Bank, and INECOBANK account for a combined total of approximately 58%.
In terms of net profit for the first nine months of 2026, Ardshinbank retained its leadership, with Ameriabank, Acba Bank, and INECOBANK holding 2nd, 3rd, and 4th positions, and IDBank moving up to 5th. These five banks collectively accounted for Over 70% of the sector's profits are generated, with the top two accounting for almost 51%.
It should be noted that with the entry of Fast Bank in November 2022, the number of banks in Armenia reached 18, but later in 2024, with the entry of HSBC, the number of banks dropped again to 17. Thus, in 2024, Ardshinbank acquired HSBC Bank Armenia. With HSBC's exit from Armenia, three subsidiaries of foreign banks now operate in the country's banking sector instead of four: VTB (Russia), Mellat (Iran), and Byblos Bank (Lebanon).
Furthermore, the presence of international institutional investors, represented by the European Bank for Reconstruction and Development (EBRD) and the Asian Development Bank (ADB), which had stakes in Ameriabank, has also decreased. In particular, with the addition of Bank of Georgia Group PLC (BOGG, later renamed Lion Finance Group PLC in 2025 after a major rebranding) and JSC Bank of Georgia as Ameriabank shareholders in 2024, with a combined 90% stake, the EBRD's stake was reduced to 10%, and ADB's stake was reduced to zero.
(The AMD/USD exchange rate as of September 30, 2026, was 362.83 AMD/$1).